

If you bought your home in North County San Diego 10, 20 or 30 years ago, you’ve probably built up a considerable amount of equity. You may have paid off your mortgage entirely.
Your adult children, meanwhile, are looking at a very different housing market.
They might have good careers, solid incomes, and money saved. But between San Diego home prices, mortgage rates, and the cost of raising a family, buying a home near where they grew up can seem almost impossible.
I speak with homeowners throughout North County San Diego who are in a position to help their children financially. Often, their wealth is tied up in real estate they’ve owned for decades.
The question is how to put some of that wealth to work for the next generation.
- Can you give your child $100,000 or $250,000 toward a down payment without paying gift tax?
- Would it be smarter to lend them the money?
- And what happens to your estate if you make a substantial gift now instead of leaving the money as an inheritance?
There are several ways to approach this, and some of the tax rules are more favorable than many parents realize.
Can You Give Your Child $100,000 or More Without Paying Gift Tax?
Yes. In many cases, you can give your adult child $100,000, $250,000, or even more without owing federal gift tax at the time of the gift.
There’s a common misunderstanding about how gift taxes work. You may have heard that the IRS limits how much you can give someone each year. For 2026, that amount is $19,000 per person.
But $19,000 is not the maximum you can give without paying gift tax.
It’s the annual gift-tax exclusion, meaning the amount you can generally give an individual each year without using any of your lifetime federal gift and estate-tax exemption.
For 2026, the IRS allows:
- $19,000 per recipient, per donor: The annual gift-tax exclusion.
- $38,000 from a married couple: Each spouse can generally give $19,000 to the same recipient, provided the gifts are properly structured.
- $15 million per person: The federal lifetime gift and estate-tax basic exclusion amount for 2026, subject to adjustments for previous taxable gifts and other applicable rules.
That last number is the one many people don’t know about.
The annual exclusion and lifetime exemption work together. You can generally give more than the annual exclusion without paying immediate federal gift tax, provided you have sufficient unused lifetime exemption.
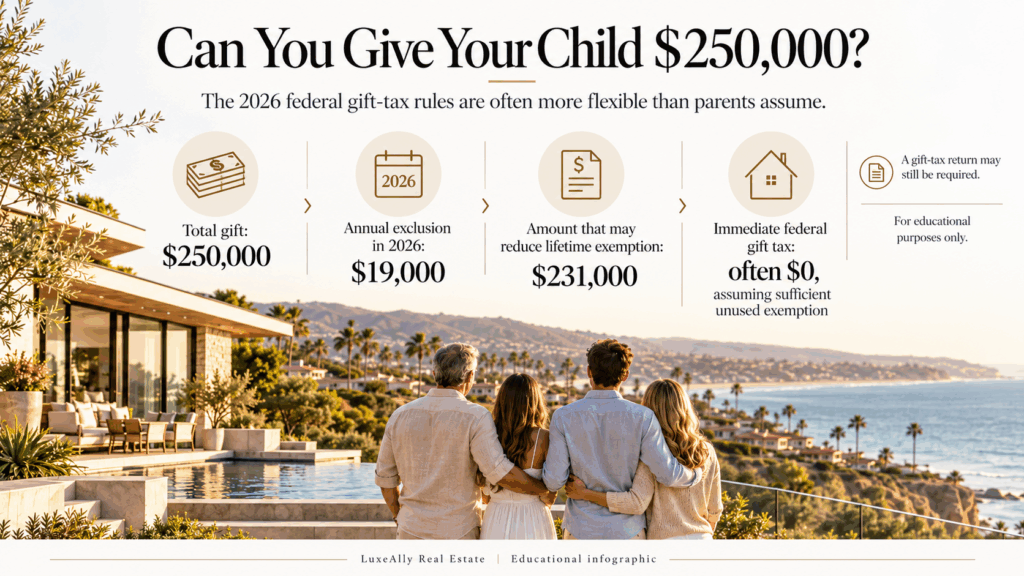

Example: Giving Your Daughter $250,000 Toward a Home
Suppose you want to give your daughter $250,000 to help her purchase a home in Encinitas.
Assuming you’re making the gift individually, haven’t made other gifts to her during the year, and have sufficient unused lifetime exemption, here’s how the federal gift-tax calculation would generally work in 2026.
The first $19,000 falls under your annual exclusion.
The remaining $231,000 counts against your $15 million lifetime gift and estate-tax exclusion.
Your immediate federal gift-tax bill would be $0.
You would generally need to report the gift to the IRS using Form 709, but filing a gift-tax return doesn’t automatically mean you owe gift tax.
Your daughter also generally wouldn’t owe federal income tax simply because she received the cash.
California doesn’t impose a separate state gift tax, either.
The important distinction is that you have used $231,000 of your lifetime federal exemption, leaving less available for future taxable gifts and your estate.
For someone with significant wealth, that reduction deserves consideration. For someone whose estate is expected to remain well below the federal estate-tax threshold, the immediate tax implications may be relatively modest.
Either way, speak with your CPA before transferring a substantial amount of money.
You can review the current limits directly on the IRS estate and gift-tax guidance page.
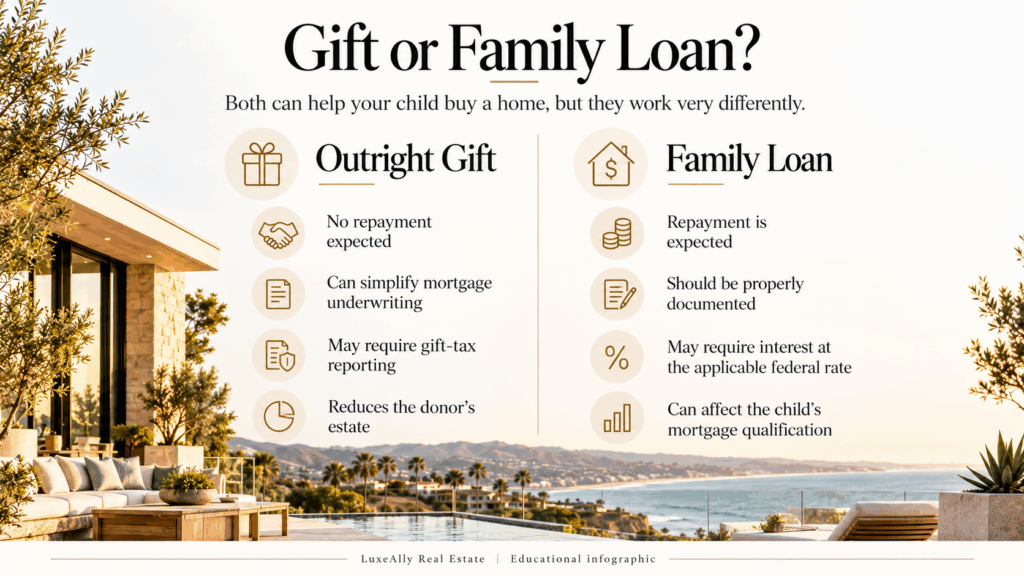
Is It Better to Gift Your Child Money or Make a Family Loan?
This is where the decision becomes more personal.
Let’s say your son and his wife have found a $1.5 million home in Carlsbad. They’ve saved $100,000, but would like to put $300,000 down.
You could give them the additional $200,000. Or you could lend it to them with the expectation that they’ll eventually pay you back.
Both approaches can help them purchase the home, but the financial consequences are different.
Option 1: Give Them the Money Outright
A gift is generally the simplest arrangement if you can comfortably afford it.
Your child receives the funds without taking on another debt. That can make mortgage qualification easier, assuming the funds are properly documented and accepted by the lender.
The gift can also be part of a larger estate-planning strategy. Instead of leaving all your assets to your children after your death, you’re transferring some of your wealth while you’re alive.
There is something appealing about that. You get to see your children establish themselves, perhaps purchase a home near you, and enjoy the benefits of the money you’ve worked to accumulate.
But the money is no longer yours.
If your financial circumstances change, you cannot simply demand that a genuine gift be returned. And if you have other children, you may need to consider how the gift affects their eventual inheritance.
Option 2: Lend Your Child the Money
A family loan can make sense if you want to help but aren’t comfortable permanently giving away a substantial amount of your assets.
Perhaps you have $500,000 available but expect to need some of that money later in retirement.
A properly structured loan allows you to provide funds now while retaining a legal right to repayment.
Your child might also benefit from an interest rate lower than what a bank would offer, subject to the IRS rules discussed below.
But a family loan should be treated like a real loan, even when everyone has the best intentions.
That means documenting the amount borrowed, the interest rate, when payments are due, and what happens if your child cannot repay you.
Without those details, the arrangement can become a source of disagreement later.
Option 3: Make Part of It a Gift and Part a Loan
You don’t necessarily have to choose one or the other.
You might give your child $100,000 as a down payment gift and provide another $150,000 as a documented family loan.
The gift reduces the amount your child needs to borrow, while the loan allows you to retain a claim on part of the money.
However, the child’s mortgage lender must approve the arrangement. The family loan could affect their debt-to-income ratio, and some mortgage programs may have restrictions on borrowed down payment funds or additional financing.
Discuss the proposed structure with the lender before moving any money.
Can You Give Your Child an Interest-Free Loan to Buy a House?
Parents sometimes assume they can simply lend their children money without charging interest.
The IRS has rules designed to prevent certain interest-free or below-market loans from being used to avoid taxes.
These rules involve something called the Applicable Federal Rate, or AFR.
The IRS publishes these rates monthly. Different rates apply depending on the length of the loan.
When a family loan falls below the applicable minimum rate, the IRS may treat some of the interest that should have been charged as income to the parent and, potentially, a gift to the child.
This is known as imputed interest.
For example, suppose you lend your son $200,000 for ten years. You agree that he’ll repay the money but won’t owe any interest.
Even though no interest is being collected, federal tax rules may still attribute interest income to you.
There are exceptions and special rules, but assuming that an interest-free family loan has no tax consequences can be an expensive mistake.
The safer approach is to have an attorney prepare a promissory note, use the appropriate AFR when required, establish a realistic repayment schedule, and keep records of payments.
If the loan is secured by the property, the documentation may also include a deed of trust. The mortgage lender will need to approve any additional lien or financing arrangement.
Interest received by the parents is generally taxable income.
One more consideration: If you later decide to forgive all or part of the loan, the forgiven amount may be treated as a gift and require gift-tax reporting.
An informal agreement between family members may feel easier. A properly documented arrangement is usually better protection for everyone.
How Does a Down Payment Gift Affect Your Child’s Mortgage Approval?
Before writing a check, your child should speak with their mortgage lender.
Mortgage companies need to verify where a buyer’s funds are coming from. This is especially important when purchasing an expensive property that requires jumbo financing.
If you’re giving your child money for a down payment, the lender will typically request a gift letter.
That letter generally identifies the donor, states the amount being provided, explains your relationship to the borrower, and confirms that no repayment is expected.
The lender may also require bank statements or other documents showing where the money originated and how it was transferred.
Under Fannie Mae’s gift-fund guidelines, eligible gifts can be used for certain down payments, closing costs, and reserves, subject to the loan’s requirements.
Jumbo lenders may apply different standards.
A gift and a loan are not interchangeable when applying for a mortgage.
If the money must be repaid, it needs to be disclosed as a loan. Calling it a gift to make mortgage approval easier can create serious legal problems.
The best time to discuss the source of the down payment is before your child begins making offers, not a few days before closing.
What if You Have More Than One Child?
Giving one child $250,000 toward a home may be straightforward financially. Explaining how that gift fits into your estate plan can be more complicated.
Consider a family with three adult children.
One lives in Encinitas and wants to buy a home. Another owns a house in another state. The third is renting and has no immediate plans to purchase.
Do you give all three children the same amount? Do you help the first child now and make adjustments later? Or do you consider the money an advance on their inheritance?
There’s no universal answer.
Some parents want to treat each child equally. Others prefer to provide help based on individual circumstances.
Neither approach is necessarily wrong, but it should be discussed and documented.
If you want the gift to count against a child’s future inheritance, your estate-planning attorney should address that in your trust or estate documents rather than relying on a verbal understanding.
The same applies to family loans. An outstanding loan may become an asset of your estate if you pass away before it’s repaid.
What if Your Child Is Married?
This is another issue worth discussing before making a large gift.
Under California law, property received by one spouse as a gift is generally considered that spouse’s separate property.
But what happens when the money is deposited into a joint bank account or used to purchase a home titled in both spouses’ names?
The answer can depend on how the funds were transferred, the title was taken, and any agreements between the spouses.
If your intention is to give money specifically to your son or daughter, rather than to the married couple jointly, speak with a California estate-planning or family-law attorney about properly documenting that intention.
It’s an uncomfortable subject, but far easier to address before a problem arises.
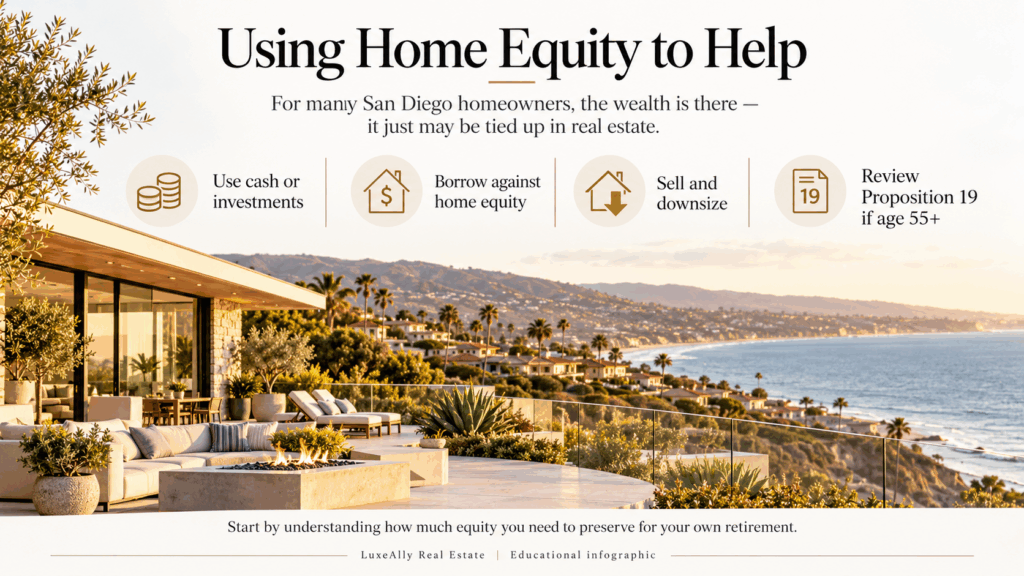
What if Most of Your Money Is Tied Up in Your Home?
This is particularly relevant to homeowners in Rancho Santa Fe, Encinitas, Del Mar, and Carlsbad.
You may own a property worth $4 million or $5 million, have a relatively small mortgage, and still prefer not to withdraw $300,000 from your investment accounts.
That doesn’t mean you don’t have the financial capacity to help your children. It means your assets aren’t particularly liquid.
Homeowners in this situation generally have a few options.
Borrow Against Your Home Equity
A home equity line of credit or other home-equity loan may allow you to access some of your property’s value without selling.
But borrowing against your home introduces another financial obligation. You need to consider the interest expense, repayment terms, possible variable rates, and how the debt affects your retirement income.
You’ll also want to review the tax treatment of the interest. Borrowing against your home to provide money to your children generally does not make the interest deductible as qualified home mortgage interest.
This approach should be evaluated with your financial advisor and tax professional.
Sell Your Larger Home and Downsize
For some families, this could be the more practical option.
Maybe you’ve owned a 5,000-square-foot home in Rancho Santa Fe for 25 years. Your children have moved out, several rooms are rarely used, and maintaining the property takes more time and money than it once did.
You’ve already been thinking about moving to something smaller.
Selling the larger home could potentially free up enough equity to purchase a replacement property, strengthen your retirement reserves, and provide financial assistance to your children.
Of course, you need to account for selling expenses, any mortgage payoff, replacement housing costs, and potential capital gains taxes. Longtime homeowners with substantial appreciation may have taxable gains beyond the federal primary-residence exclusion.
The decision should start with how much money you need to keep, not how much you can give away.
But if downsizing already makes sense for your lifestyle, helping your children may become one more reason to consider it.
I’ve written separately about why downsizing and selling a longtime North County San Diego home can be more complicated than homeowners expect.
Don’t Forget About Proposition 19
California’s Proposition 19 may also play a role in the decision.
Under qualifying circumstances, homeowners age 55 and older can sell their primary residence and transfer its existing property-tax base to a replacement primary residence elsewhere in California.
That can be particularly valuable for someone who bought a home decades ago and currently pays property taxes based on an assessed value far below its market value.
The rules include timing, qualification, and replacement-home value requirements. Purchasing a more expensive replacement property can result in an adjustment to the transferred tax base.
Proposition 19 doesn’t eliminate capital gains taxes, and it doesn’t directly provide a tax exemption for gifts to children.
It can, however, make downsizing more financially attractive for eligible homeowners who would otherwise face a substantial increase in property taxes.
Before making a decision, review your eligibility with a qualified tax professional.
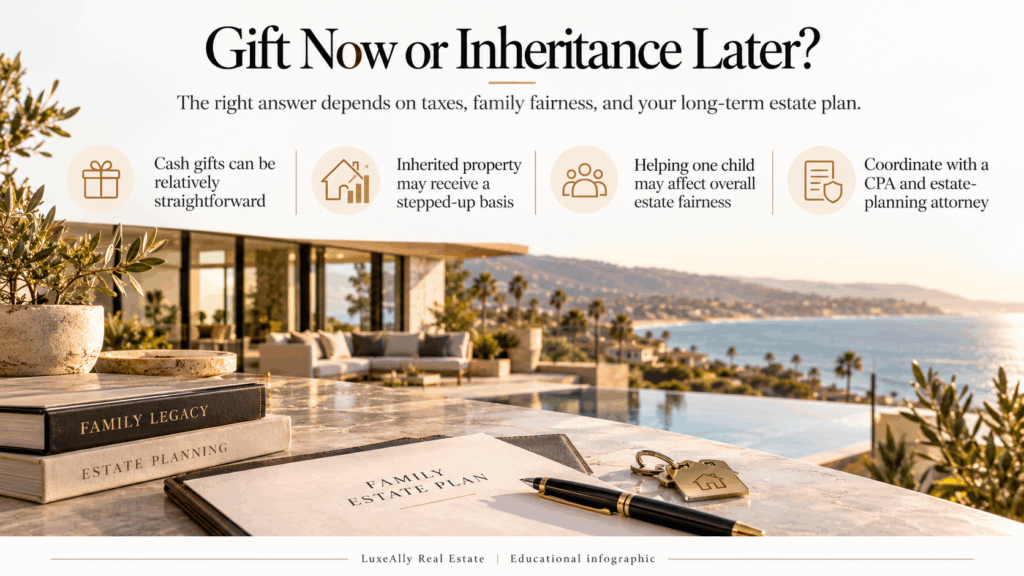
Is It Better to Give Your Kids Money Now or Leave It as an Inheritance?
This is an important question, especially for families with substantial real estate holdings.
There’s a meaningful tax difference between giving someone cash and transferring appreciated property.
If you give your child cash, they generally receive it without federal income tax on the gift itself.
If you give them a property or other appreciated asset, the capital gains consequences can be very different.
Why Gifting a House Can Be More Complicated
Suppose you purchased a property many years ago for $500,000 and it’s now worth $2 million.
If you give that property to your child during your lifetime, they generally receive your adjusted tax basis rather than a new basis equal to its current market value.
That means if they later sell the property, they could face capital gains taxes on appreciation that occurred long before they owned it. The exact result depends on basis adjustments, exclusions, and other circumstances.
In contrast, qualifying property inherited after a parent’s death generally receives a tax basis based on its fair market value at the date of death.
This is commonly called a step-up in basis.
That distinction can make a substantial difference when dealing with highly appreciated real estate.
California also has separate property-tax considerations.
Under Proposition 19, a child generally must use an inherited parent’s qualifying principal residence as their own principal residence to receive the applicable parent-child property-tax reassessment exclusion. Value limits and filing requirements apply.
For qualifying transfers from February 16, 2025, through February 15, 2027, the inflation-adjusted exclusion amount is $1,044,586 above the property’s qualifying factored base-year value. That is not a blanket exclusion of the first $1,044,586 of market value.
Gifting the family home simply to avoid probate or help a child financially could therefore create tax consequences that outweigh the intended benefit.
Before transferring title to an appreciated property, have your CPA and estate-planning attorney compare the tax consequences of gifting it now, transferring it through a trust, and leaving it as an inheritance.
Five Questions to Ask Before Helping Your Child Buy a Home
Before committing to a substantial gift or family loan, I would encourage parents to think through five questions.
1. Can you comfortably afford to give away the money?
Having significant net worth doesn’t necessarily mean you have unlimited cash available. Consider your retirement, healthcare needs, future housing costs, and the possibility of unexpected expenses.
2. Is this truly a gift, or do you expect to be repaid?
Be clear with yourself and your children. If you expect repayment, document a legitimate loan from the beginning.
3. How will this affect your other children?
Think about whether you want to make equal gifts, provide different amounts based on need, or account for the assistance in your estate documents.
4. Can your child afford the home after purchasing it?
A larger down payment can reduce the mortgage and may improve the financing terms, but it won’t eliminate property taxes, homeowners insurance, maintenance, or HOA expenses.
Helping someone purchase a house they cannot afford to maintain isn’t necessarily doing them a favor.
5. Have you spoken with the right professionals?
A CPA can explain the tax implications. An estate-planning attorney can address trusts, gifts, and family loans. The mortgage lender can confirm how the financial assistance must be structured.
If the plan involves selling or borrowing against real estate, an experienced local real estate advisor can help you understand your options.
You Don’t Have to Wait for an Inheritance to Help Your Children
For many parents, the goal of accumulating wealth was never just to have a larger bank account. It was to create security and opportunity for their family.
If you’re in a position to help your adult children purchase a home, there’s something meaningful about being able to do that while you’re still here to enjoy it with them.
Maybe it means your children can afford to live in Encinitas rather than moving out of San Diego County. Maybe it means the grandchildren grow up a few minutes away instead of several hours away.
Or perhaps it means helping your son or daughter purchase their first home several years earlier than they otherwise could.
Of course, not every family should make a large gift. Sometimes a loan makes more sense. Sometimes the best decision is to preserve your wealth and leave it to your children through your estate.
The important thing is understanding your options before making that decision.
Considering Downsizing or Using Your Home Equity to Help Your Family?
I work with homeowners throughout Rancho Santa Fe, Encinitas, Carlsbad, Del Mar, and Coastal North County San Diego who have built substantial equity in their properties.
Sometimes they’re thinking about selling because the house is larger than they need. Other times they’re considering how to help their children while making smart decisions about their own retirement.
If you’re in that position, I’m happy to help you understand what your property might be worth, what a sale could look like, and whether downsizing might make financial sense.
There’s no obligation to sell. Sometimes understanding the numbers is all you need to make a decision.
Contact Jeff Toth for a Confidential Real Estate Consultation
Jeff Toth
Founding Partner
LuxeAlly Real Estate
Rancho Santa Fe | Encinitas | Carlsbad | Coastal North County San Diego
Phone: 858-630-8997
www.luxeally.com
Frequently Asked Questions About Helping Your Kids Buy a Home in San Diego
Yes. Parents can generally provide money toward a down payment, including for expensive homes in San Diego. The amount you can give is not limited to the IRS annual gift-tax exclusion, although larger gifts may require reporting and use part of your lifetime exemption. Your child's mortgage lender will typically require documentation confirming that the funds are a gift and do not need to be repaid.
It can. A larger down payment reduces the amount your child needs to borrow and may improve their financing options. However, jumbo lenders often have stricter requirements regarding income, cash reserves, credit history, and the source of down payment funds. Speak with the lender before transferring money, since gift-fund requirements vary.
Possibly, but the mortgage lender needs to know about the loan. If your child is borrowing money from you, that additional debt may affect their ability to qualify for financing. Some mortgage programs also restrict borrowed down payment funds. A family loan should have documented repayment terms and comply with applicable IRS interest-rate rules.
Yes. Depending on your circumstances, you may be able to access equity through a home equity line of credit, another type of loan, or the sale of your property. However, borrowing against your home introduces interest expense and repayment obligations. If you already have substantial equity and are considering downsizing, selling may be worth comparing with borrowing.
Absolutely. Some longtime North County San Diego homeowners have millions of dollars in equity but don't necessarily have that amount available in cash. Selling a larger home and moving into something smaller may free up funds for retirement, investments, and financial assistance to children. Before making that decision, calculate your net proceeds after selling expenses, mortgage payoff, potential capital gains taxes, and the cost of your replacement home.
Both approaches can help, but they involve different risks. Co-signing makes you legally responsible for the mortgage, even if your child makes all the payments. That obligation could affect your borrowing ability and finances. A down payment gift doesn't create the same ongoing mortgage liability, although you permanently give up the money. The better choice depends on your child's financial situation and your own retirement plans.
Not without understanding the consequences. Adding your child to a property's title may create gift-tax reporting requirements, property-tax reassessment issues, estate-planning complications, and potential exposure to your child's creditors. It can also affect how capital gains are calculated if the property is eventually sold. Gifting cash or establishing a properly documented family loan may be simpler, depending on your goals.
For some families, giving cash toward a home purchase is simpler than transferring an appreciated property. When you gift real estate during your lifetime, your child generally receives your adjusted tax basis. Property inherited after death may qualify for a stepped-up basis, potentially reducing future capital gains taxes. California's Proposition 19 also imposes restrictions on parent-child property-tax exclusions. Compare the alternatives with a CPA and estate-planning attorney before transferring ownership.
Important Tax and Legal Disclaimer
This article is provided for general informational and educational purposes only and does not constitute tax, legal, investment, mortgage, or estate-planning advice. Jeff Toth and LuxeAlly Real Estate are not acting as CPAs, tax advisors, attorneys, or financial planners in connection with this article. Federal gift-tax exemptions, estate-tax rules, interest rates, mortgage requirements, and California property-tax laws are subject to change. The dollar amounts and tax examples reflect rules in effect for 2026 and may not apply to every taxpayer, particularly non-U.S. persons or those with more complex estates. Before making a substantial gift, establishing a family loan, transferring property, or selling real estate for estate-planning purposes, consult a qualified CPA, California estate-planning attorney, financial advisor, and mortgage professional as appropriate.


